Archive

January 2025

Browsing

Strategic financial planning is crucial for business growth. It guides decisions, helping businesses avoid pitfalls and seize opportunities. Imagine it as a roadmap, ensuring businesses stay on track toward goals. This planning involves three key elements: setting financial goals, analyzing current financial status, and creating actionable steps to achieve these goals. For instance, in San Antonio small business accounting, strategic planning ensures that resources are allocated efficiently. It helps businesses manage cash flow, reduce costs, and prepare for unexpected challenges. Without a clear financial plan, businesses may struggle to measure success or identify areas needing improvement. History shows that businesses with robust financial plans often experience steady growth and stability. By focusing on strategic financial planning, businesses can not only survive but thrive in competitive markets. It’s a disciplined approach that fosters long-term success and sustainability. So, let’s explore how strategic financial planning can transform business operations and fuel growth.

Setting Financial Goals

The first step in strategic financial planning is setting clear financial goals. Goals should be specific, measurable, and aligned with the overall mission of the business. For example, a business might aim to increase its revenue by 20% in the next fiscal year. This goal provides a target and motivates the team to work toward it. Setting goals also helps in prioritizing resources and efforts.

Analyzing Current Financial Status

Before planning for the future, it’s important to understand where the business stands financially. This involves reviewing financial statements and identifying trends or areas for improvement. Businesses can use this analysis to make informed decisions about investments and cost management. Analyzing financial health also aids in risk management and preparing for economic shifts.

Creating Actionable Steps

With goals set and a clear understanding of the current financial status, the next step is developing a plan with actionable steps. This plan outlines the strategies and actions needed to achieve financial goals. It might include budget adjustments, cost-saving initiatives, or investment in new technologies.
The Role of Cash Flow Management

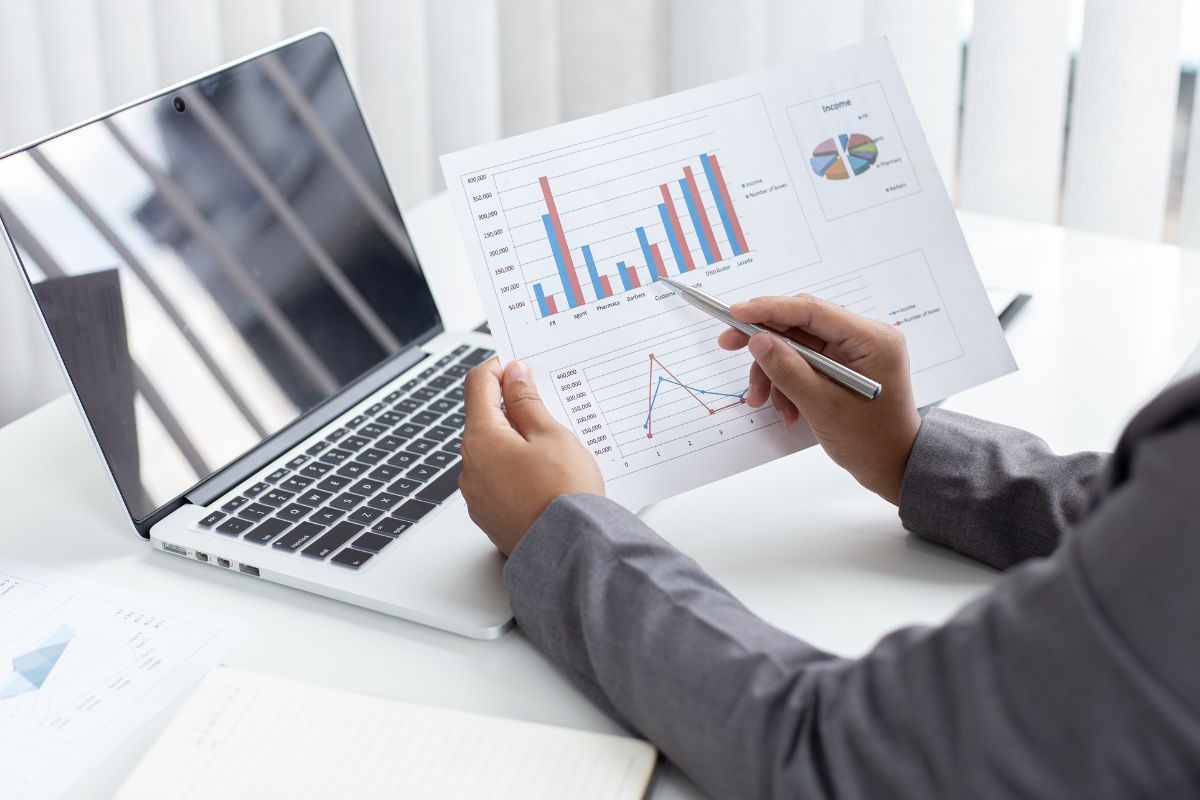
Effective cash flow management is a cornerstone of strategic financial planning. Cash flow refers to the money moving in and out of a business. By managing cash flow effectively, businesses ensure they have enough funds to cover expenses and invest in opportunities. A good cash flow plan helps avoid financial strain and supports business stability.

Benefits of Strategic Financial Planning

Strategic financial planning offers several benefits:

  • Improved Decision-Making: Helps businesses make informed choices.
  • Resource Optimization: Allocates resources where they are most needed.
  • Risk Management: Prepares businesses for economic changes.

Comparison of Businesses With and Without Strategic Financial Plans

Aspect With Strategic Plan Without Strategic Plan
Decision-Making Informed and precise Reactive and uncertain
Resource Allocation Efficient and targeted Haphazard and wasteful
Growth Consistent and sustainable Erratic and unstable

Preparing for Economic Changes

A strategic financial plan prepares businesses for economic fluctuations. By anticipating changes and planning accordingly, businesses can maintain stability. This might involve setting aside reserves or diversifying investments to reduce exposure to market volatility. For more information on managing economic changes, the U.S. Small Business Administration provides valuable resources.

Implementing Strategic Financial Planning

Implementing a strategic financial plan involves commitment and regular review. Businesses should periodically assess their financial plans and adjust them as needed. This ensures the plan remains relevant and effective in achieving business goals. Regular evaluation helps identify new opportunities and address unforeseen challenges promptly.

Conclusion

In conclusion, strategic financial planning is essential for sustainable business growth. By setting clear goals, analyzing the current financial status, and developing actionable steps, businesses create a solid foundation for success. Effective cash flow management and preparation for economic shifts further enhance stability and growth. A strategic financial plan is not just a document; it is an ongoing process that supports a business’s long-term vision. For those looking to dive deeper into strategic planning, the Small Business Administration’s guide can be a helpful starting point.
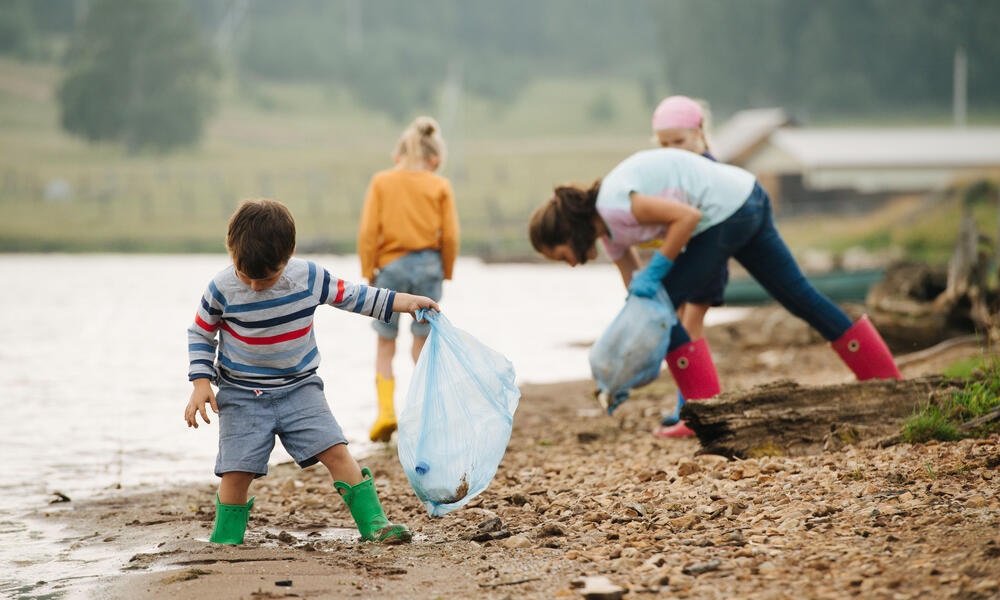
The primary reason for protecting waterways is to ensure the sustainability of the environment. A healthy ecosystem relies on water bodies to maintain its delicate balance. There is a wide variety of plants and animals living there, many of which are unique to certain regions. The overall health of our planet needs to protect these habitats to conserve biodiversity.

Economic growth and development

The benefits of protecting waterways extend beyond environmental concerns and contribute significantly to economic growth and development. Various industries, such as agriculture, fishing, tourism, and manufacturing, depend on readily accessible water sources. A healthy river or lake, for example, provides irrigation water, which is crucial for food production and farming livelihoods.

A large part of the tourism industry depends on the beauty and health of waterways. From fishing and boating to scenic river cruises, tourism contributes substantially to the economic well-being of local communities. By preserving and promoting clean and attractive water bodies, regions attract visitors, create jobs, and boost their economies.

The presence of healthy waterways enhances property values and attracts businesses and investors. Water quality and reliability are two of the most important factors that contribute to industrial processes. In this way, protecting waterways leads to greater investment, job creation, and overall economic prosperity.

Social well-being and quality of life

Protecting waterways directly influences the social well-being and quality of life within communities. Safe drinking water is a fundamental human right, and maintaining healthy waterways ensures a steady supply of safe water for homes, schools, and healthcare centres. This not only lowers the risk of waterborne diseases but also enhances overall public health.

Waterways also provide recreational opportunities, offering spaces for relaxation, exercise, and connection with nature. Taking a stroll on the riverbank, enjoying a refreshing swim in the lake, or going kayaking all contribute to physical and mental wellbeing. A city’s green spaces and water bodies reduce stress and improve the quality of life.

Protecting waterways fosters a sense of community and cultural identity. It is integral to the traditions and way of life of many indigenous groups, like the HDI Six Nations, to have a deep connection to their local water bodies. By preserving these waterways, we honour and respect their cultural heritage and foster social cohesion.

Collaborative efforts and partnerships

The task of protecting waterways is a collective endeavour that requires collaboration and partnerships between various stakeholders. To implement effective conservation strategies, governments, non-profit organizations, and local communities must collaborate. This includes initiatives such as:

  • Implementing sustainable water management practices to reduce pollution and conserve water resources.
  • Restoring and rehabilitating degraded water bodies through initiatives like river clean-up drives and wetland restoration projects.
  • Enhancing public awareness and education about water conservation and waterway degradation.
  • Encouraging sustainable fishing practices to ensure the long-term viability of aquatic ecosystems and fish populations.
  • Setting up protected areas and marine reserves to protect vital habitats and biodiversity.

By engaging in these collaborative efforts, we create a more sustainable for our waterways and the communities that depend on them.

Running a nonprofit is a meaningful endeavor, but it comes with its own set of challenges. One key challenge is managing finances. While some think any accountant can handle nonprofit finances, this isn’t true. Nonprofits have unique needs. They must follow specific regulations. That’s why finding an accountant for nonprofits in Myrtle Beach, SC, can make a big difference. A specialized accounting firm has the expertise to navigate these complexities. They understand tax-exempt status and can help avoid costly errors. They ensure accurate financial reporting, which is crucial for maintaining trust with donors. These firms also assist with audits and compliance. When choosing such an accountant, you ensure that your nonprofit has a partner who truly understands your financial landscape. This partnership can lead to better decision-making, allowing your organization to focus on its mission more effectively. In the end, specialized attention can lead to positive outcomes.

Understanding the Unique Needs of Nonprofits

Nonprofits operate under a different set of rules compared to for-profit businesses. They rely on funding from donations, grants, and memberships, which requires transparent financial practices. A specialized accounting firm understands these differences. They can help your nonprofit comply with regulations specific to tax-exempt organizations.

The Importance of Accurate Financial Reporting

Accurate financial reporting is crucial for maintaining transparency and trust with donors, supporters, and stakeholders. When financial reports are accurate and reliable, they reflect the nonprofit’s integrity. Financial mismanagement can lead to a loss of confidence and reduced funding. A specialized accounting firm ensures that your financial statements are clear and compliant with the requirements set by the IRS.

Benefits of Hiring a Specialized Accounting Firm

Here are three significant benefits of hiring a specialized accounting firm for your nonprofit:

  • Expertise in Nonprofit Accounting: They have a deep understanding of nonprofit accounting standards, including the Generally Accepted Accounting Principles (GAAP).
  • Efficiency and Accuracy: A specialized firm can streamline accounting processes, making them more efficient and less prone to errors.
  • Compliance Assurance: They help your nonprofit meet the requirements of regulatory bodies, reducing the risk of penalties.

Comparison: General Accountant vs. Nonprofit Specialist

Feature General Accountant Nonprofit Specialist
Understanding of Nonprofit Tax Codes Basic Advanced
Experience with Donor Reporting Limited Extensive
Ability to Handle Audits General Specialized

Ensuring Audit and Compliance Readiness

Regular audits are a part of a nonprofit’s life. A specialized accounting firm prepares your organization for these audits. They identify potential issues before they become problems. This preparation ensures that your nonprofit remains in good standing with regulatory bodies. More information on compliance can be found on the National Council of Nonprofits website.

Making Informed Financial Decisions

With accurate data, nonprofits can make informed financial decisions. A specialized firm provides insights into financial trends and patterns. These insights help in planning and budgeting, ensuring that resources are used effectively. Nonprofits can allocate funds where they are needed most, maximizing their impact.

Conclusion

Nonprofits need a specialized accounting firm to handle their unique financial challenges. With expertise and understanding of nonprofit regulations, these firms provide the support needed for accurate financial reporting and compliance. This support is vital for transparency and trust with donors and stakeholders. Hiring a specialized firm means better decision-making and efficient use of resources. In the end, this choice benefits the nonprofit’s mission and its community impact. It’s a decision that offers both peace of mind and tangible results.

Choosing between accounting firms and in-house accountants is a significant decision for any business. Both options have unique benefits and potential drawbacks. Accounting firms offer a team of experts who can handle complex financial tasks. They bring a wealth of experience from working with diverse clients. In contrast, hiring an in-house accountant means having someone dedicated to your finances. This person can provide immediate solutions and focus attention on your specific needs. For those in Florida, searching cpa cape coral might reveal local firms or individuals with knowledge of state regulations. Understanding these options helps in making a choice that aligns with your business goals. Key factors to consider include cost, expertise, and availability. An informed decision can lead to better financial health for your business. This blog will explore the advantages and considerations for both options, guiding you to find the best fit.

Advantages of Accounting Firms

Accounting firms can be a great choice for businesses that need a broad range of services. Here are a few reasons why they might be the right option:

  • Expertise: Firms often have multiple accountants and specialists. This can be beneficial when handling complex financial issues.
  • Scalability: As your business grows, an accounting firm can easily adjust to your needs.
  • External Perspective: Firms offer an outside view, which can help in identifying inefficiencies or areas of concern.

Firms are also continuously updating their knowledge to adhere to the latest financial regulations. This is particularly important for businesses working across multiple jurisdictions.

Advantages of In-House Accountants

Hiring an in-house accountant offers distinct benefits that are worth considering:

  • Dedicated Focus: In-house professionals are solely focused on your business. This can lead to better-tailored financial strategies.
  • Immediate Availability: Having an accountant on-site allows for immediate response to financial queries or issues.
  • Company Culture: An in-house accountant becomes part of the company culture, which can foster better communication and understanding.

An in-house accountant can become a key team member, contributing to strategic decisions. For guidelines on hiring, the U.S. Small Business Administration provides valuable resources.

Cost Considerations

Cost can be a crucial factor in deciding between an accounting firm and an in-house accountant. Here’s a simple comparison table:

Accounting Firm In-House Accountant
Variable fees based on services needed Fixed salary and benefits
Potentially higher upfront costs Consistent monthly expense
No additional overhead costs Office space and equipment costs

Accounting firms often charge for services on an as-needed basis, which can be advantageous for businesses that require occasional assistance. In contrast, an in-house accountant presents a steady monthly expense but also includes costs like employee benefits and office space.

Making the Right Choice

When deciding between an accounting firm and an in-house accountant, reflect on the specific needs of your business. Consider the complexity of your financial situation, the desired level of expertise, and how much personal attention your business demands.

For a growing business that needs a variety of services, an accounting firm might offer the flexibility and expertise needed. On the other hand, if personal attention and immediate availability are priorities, an in-house accountant could be more suitable. Weigh these factors carefully to ensure your choice supports your business’s financial health and growth.

Ultimately, the decision should align with your business strategy and financial goals. Making an informed choice can lead to a more sustainable and prosperous financial future.

Understanding the roles of an accountant and a Certified Public Accountant (CPA) is crucial when managing finances. Both positions play a key part, but their responsibilities, qualifications, and services differ. An accountant generally handles routine financial tasks like bookkeeping and preparing reports. A CPA, on the other hand, holds a special certification that allows for more advanced services. This certification requires passing a rigorous exam and meeting strict education and experience criteria. CPAs can represent clients in front of the IRS and offer insights into complex financial strategies. For example, if you’re looking for expert financial guidance in tax planning or auditing, a Pineville, Louisiana CPA would have the qualifications to meet these needs. The difference between these roles is not just in the title but in the level of expertise and services they offer. By understanding these distinctions, you can make informed decisions about your financial needs.

Responsibilities of an Accountant

An accountant performs essential financial duties. These duties include tracking income and expenses, preparing financial reports, and ensuring accurate record-keeping. Accountants play a vital role in the day-to-day financial operations of businesses and individuals. They often use software to manage transactions and ensure compliance with financial regulations. While they do not need certification to work, accountants can choose to pursue further credentials to enhance their expertise.

Responsibilities of a Certified Public Accountant (CPA)

CPAs have a broader range of responsibilities, thanks to their extensive training and certification. These professionals handle more complex financial matters like auditing, tax planning, and consulting. CPAs can represent clients in disputes with the IRS, which adds a layer of trustworthiness and authority to their role. The CPA credential is acquired by meeting stringent educational requirements and passing the CPA exam.

Qualifications and Certification

Accountants typically hold a bachelor’s degree in accounting or a related field. This education provides the foundation for understanding financial practices and principles. CPAs, however, must complete additional coursework in accounting and business, followed by the Uniform CPA Examination. This exam tests candidates on various accounting topics, ensuring they have the expertise needed for complex financial tasks.

Comparative Table: Accountant vs. CPA

Aspect Accountant CPA
Education Bachelor’s degree Bachelor’s degree + additional coursework
Certification Not required Required
Services Bookkeeping, financial reports Audit, tax planning, representation before IRS

Choosing the Right Professional for Your Needs

When deciding between an accountant and a CPA, consider your financial needs. For routine tasks like managing daily finances and preparing simple reports, an accountant could be sufficient. If you face complex tax issues, need an audit, or require representation before the IRS, a CPA is more suited to provide these services.

Regulatory and Ethical Standards

CPAs adhere to strict ethical standards due to their certification. This includes maintaining confidentiality and providing honest, accurate advice. Regulatory bodies oversee CPAs to ensure compliance with these standards. Learn more about these standards through the National Association of State Boards of Accountancy (NASBA). Accountants also follow ethical guidelines, but they do not face the same level of professional scrutiny as CPAs.

Conclusion

Both accountants and CPAs offer valuable services, but the choice between them depends on your specific financial needs. Understanding their roles, responsibilities, and qualifications can guide you in selecting the right financial professional. Whether you need basic bookkeeping or complex financial advice, knowing the difference helps ensure your financial health is in good hands.

Virtual accountants are transforming financial management in ways that are both practical and innovative. These professionals offer services that are efficient, cost-effective, and accessible. With the rise of technology, businesses no longer need to rely on in-house accountants. Instead, they can hire a remote accountant in Pompano Beach or anywhere else in the world. This shift provides businesses with greater flexibility and access to a broader talent pool. Virtual accountants handle tasks such as bookkeeping, tax preparation, and financial analysis. They do this with precision and speed. This new approach allows businesses to focus on their core activities. Virtual accountants also bring expertise and a fresh perspective to financial planning. This can help companies make informed decisions. By using digital tools, they ensure that financial data is secure and up to date. In this blog, I will explore how virtual accountants are changing the landscape of financial management.

The Benefits of Virtual Accountants

Virtual accountants offer several clear advantages over traditional in-house accountants. Here are three key benefits:

  • Cost-Effectiveness: Virtual accountants reduce overhead costs. Businesses save on salaries, office space, and benefits.
  • Flexibility: Companies can choose from a global pool of experts. This allows them to find the perfect match for their specific needs.
  • Scalability: Businesses can easily scale accounting services up or down, depending on their needs. This adaptability is crucial for growing companies.

How Virtual Accountants Work

Virtual accountants use a combination of cloud-based software and communication tools to manage financial tasks. They securely access financial data through platforms that keep information safe and up-to-date. These platforms often include features for bookkeeping, invoicing, and tax management. Regular meetings and communication happen through video calls and emails, ensuring smooth operations. Moreover, virtual accountants provide real-time insights, helping businesses make informed decisions quickly.

Virtual vs. Traditional Accountants: A Comparison

Aspect Virtual Accountants Traditional Accountants
Location Remote, global In-office, local
Cost Variable, often lower Fixed, often higher
Flexibility High Limited
Scalability Easy to scale Challenging to scale
Technology Cloud-based May use outdated systems

Security and Compliance

Security is a top concern for businesses considering virtual accountants. Fortunately, these professionals use advanced security measures to protect financial data. Many virtual accounting services comply with industry standards and regulations, ensuring that data stays confidential and secure. For more details on data protection, you can refer to the Federal Trade Commission’s guide on data security.

The Future of Financial Management

The trend towards virtual accounting is growing. As technology advances, more businesses will likely adopt this model. This shift is not just about convenience. It is about transforming how businesses manage their finances. Virtual accountants can provide insights and strategies that drive growth and efficiency. They help companies navigate complex financial landscapes with ease. The U.S. Small Business Administration offers resources to help businesses understand the benefits of modern financial management practices.

Conclusion

Virtual accountants are revolutionizing financial management by offering cost-effective, flexible, and scalable solutions. They provide expert services that help businesses focus on growth and innovation. By embracing this new way of managing finances, companies can gain a competitive edge. The future of accounting is virtual, and it’s reshaping the business world for the better.

Keeping accurate financial records is a cornerstone of any successful small business. Yet, many small businesses stumble with bookkeeping, leading to costly errors. Mistakes in bookkeeping can affect cash flow, tax filings, and decision-making. It’s important to recognize these errors and learn how to avoid them. After all, a solid financial foundation supports growth and stability. In this blog, I will highlight ten common bookkeeping mistakes that small businesses often make. I’ll explain how these pitfalls can be avoided with simple, practical steps. Whether you’re handling your own books or considering small business bookkeeping services in Calaveras County, understanding these mistakes can save time and resources. By being proactive, small businesses can ensure their financial health remains strong. Let’s dive into these common errors and explore effective ways to steer clear of them. Building awareness and taking action can lead the way to better bookkeeping practices.

1. Not Separating Personal and Business Finances

Mixing personal and business finances is a frequent misstep. This can complicate accounting and lead to inaccurate records. To avoid this, open a separate business bank account. It simplifies the tracking of expenses and revenues. The Small Business Administration advises maintaining clear boundaries between personal and business finances.

2. Failing to Track Receipts

Many small businesses neglect to keep thorough records of their receipts. This oversight can cause issues during tax season. Keeping digital copies of receipts can enhance organization. Utilize apps or cloud-based systems to store and categorize them efficiently.

3. Ignoring Accounts Receivable

Letting unpaid invoices pile up is another common oversight. It affects cash flow and can impact business operations. Establish a routine for invoicing and follow up on overdue payments. Regularly review accounts receivable to ensure timely payments.

4. Not Reconciling Bank Statements

Skipping bank statement reconciliation can lead to unnoticed discrepancies. Reconcile your bank statements monthly to identify and resolve errors. This practice ensures that your financial records align with your actual bank balance.

5. Misclassifying Employees and Contractors

Misclassifying workers can result in costly fines. Understand the difference between employees and independent contractors. The Internal Revenue Service provides guidelines to help classify workers correctly. Proper classification helps avoid legal and financial consequences.

6. Overlooking Small Transactions

Small transactions, if ignored, can add up over time. Ensure every transaction is recorded, no matter how small. This habit leads to accurate financial records and helps monitor spending patterns.

7. Delaying Bookkeeping Tasks

Procrastinating on bookkeeping tasks can create a backlog. It increases the risk of errors and makes tax preparation more difficult. Set a regular schedule for bookkeeping activities to stay organized.

8. Not Backing Up Financial Data

Failing to back up financial data can lead to significant losses if your system crashes. Use cloud-based storage or external drives to secure your data. Regular backups ensure that your information is safe and easily recoverable.

9. Misunderstanding Financial Statements

Many small business owners lack understanding of financial statements. This can lead to poor business decisions. Learning to read balance sheets, income statements, and cash flow statements is crucial. Consider taking a basic accounting course to build this skill.

10. Failing to Plan for Taxes

Failure to plan for taxes can result in financial strain. Set aside money throughout the year to cover tax obligations. Consult with a tax professional to help with tax planning and ensure compliance with tax laws.

Comparison Table: Common Bookkeeping Mistakes vs. Solutions

Mistake Solution
Mixing finances Use separate accounts
Ignoring receipts Use digital storage
Unpaid invoices Follow up regularly
No reconciliation Monthly reviews
Worker misclassification Understand IRS guidelines

By addressing these common bookkeeping mistakes, small businesses can create a solid financial foundation. It’s about developing good habits and using available resources wisely. With the right strategies, bookkeeping becomes a manageable part of running a successful business.

Is your business prepared to deal with a fire emergency? If yes, we are confident that you have likely enlisted the services of Fire Wardens to ensure the safety of your place.

A Fire Warden is responsible for implementing the necessary fire safety measures to prevent a fire, maintaining workplace continuity, and preparing for a fire emergency. No fire emergency plan is complete without fire wardens, so understanding their responsibilities is crucial.

Here, we discuss their responsibilities in detail.

What is a Fire Warden, and What Does Fire Warden Training Involve?

Non-domestic buildings must have a designated “responsible person” for the premises. In the case of a workplace, this role may be filled by a building manager, landlord, or supervisor. It is their responsibility to ensure that the building is completely fire-safe and complies with all laws, and they must appoint fire wardens to assist them with this task. All fire wardens must complete fire warden training to ensure they understand their responsibilities and are aware of potential hazards within the building.

It is completely untrue that a fire warden’s responsibilities only start during a fire. Fire wardens, also known as fire marshals, play a vital role in the daily management of the building and usually fall into one of two categories: routine or emergency.

Emergency Planning and Drills

One of the main duties of a fire warden is to assist in developing and executing a workplace fire emergency plan. This plan describes what to do in the case of a fire, including evacuation procedures and assembly points. They also organize and participate in regular fire drills to make sure that every employee is aware of the evacuation procedure. The responsibilities include:

  • Create clear and effective evacuation routes and ensure they are free from obstacles.
  • Identify and designate secure meeting spots where staff members can gather during an evacuation.
  • Organize and supervise regular fire drills to improve the evacuation procedure.

Fire Warden

Fire Extinguishers and Alarm Checking

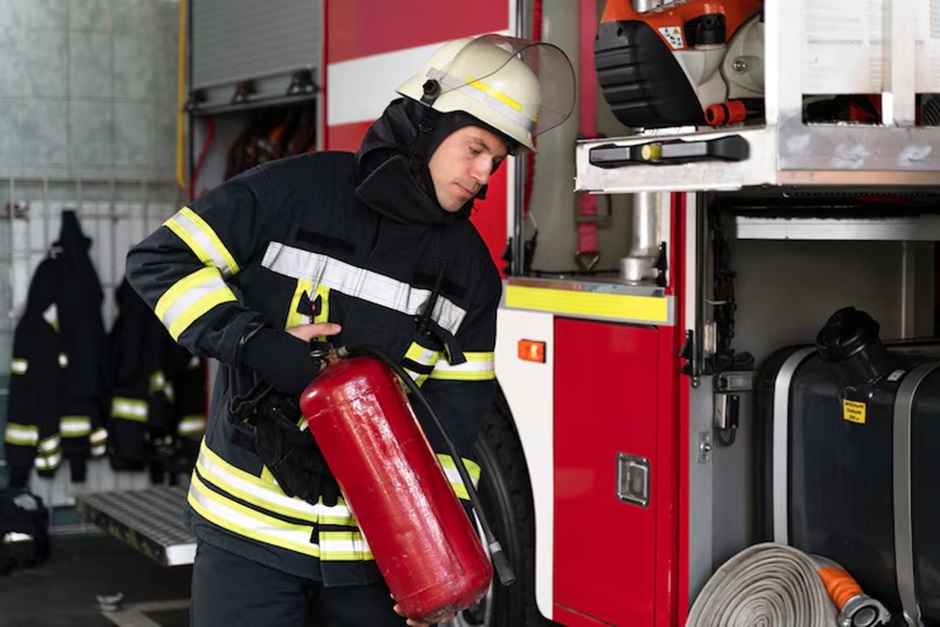
The fire alarms have been found to be malfunctioning on several occasions, and the fire extinguishers are present at places that are inaccessible when a fire breaks out. A fire warden’s primary responsibility is ensuring the fire alarms are working properly. If not, he may proceed with the necessary steps.

Additionally, he verifies whether or not fire extinguishers receive regular service. He completes this task once a month.

Safe Evacuation of Workers

Fire wardens are responsible for safely evacuating workers and visitors from a workplace after a fire alarm is sounded.

During an evacuation, a fire warden needs to:

  • Encourage everyone to evacuate the building using the proper channels and exits (and not inappropriate exits such as lifts).
  • Verify all accessible areas in the vicinity, including the bathroom, to make sure everyone has evacuated. This should be done as they leave the building so the fire warden avoids endangering themselves by returning to the evacuation area.
  • Shut the doors to help to isolate the fire.
  • Direct everyone to the assembly place and assist in checking that everyone has arrived at their destination safely.

So, fire wardens should be granted full authority to conduct evacuations, and workers should be informed of this authority.

Fire Wardens Indulge all People in Fire Safety

Indulging all people in fire safety is crucial to guarantee maximum protection from fire hazards.

Interactions between fire wardens and residents include:

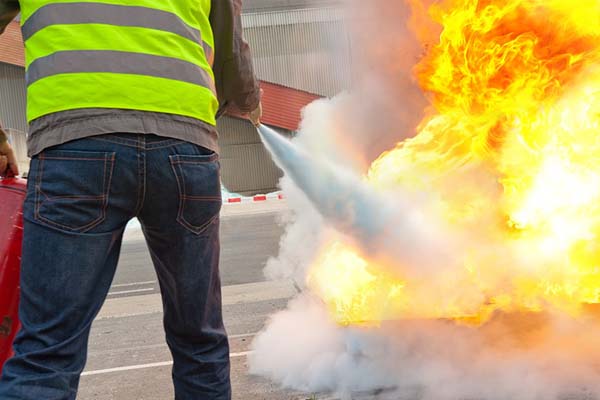
  • Raising awareness among them about workplace fire hazards, kinds of fire and fire extinguishers, and how to utilize an extinguisher.
  • Educating employees on responding in an emergency and designating distinct roles to different people.
  • Ensuring all workers fulfill their obligations and are held responsible during an evacuation.
  • Ensuring that everyone receives fire safety training. It can be updated annually.
  • Preparing all people for emergencies and aiding those with specific requirements, such as a wheelchair user, to evacuate.